How Predictive Analytics Is Used in Insurance: Real-World Impact
Learning how predictive analytics is used in insurance helps clarify why your premiums fluctuate and how companies identify potential risks before they manifest. By analyzing vast datasets, insurers shift from reactive historical reporting to proactive foresight, allowing for more personalized coverage and faster claim settlements. This transformation relies on sophisticated mathematical models that interpret behavioral patterns, environmental data, and historical trends to forecast future outcomes.
For policyholders, this means a more tailored experience, while for insurance carriers, it represents a fundamental shift in operational efficiency. This article examines the mechanics behind these models and their tangible impacts on the modern insurance landscape.
Defining Predictive Analytics in the Insurance Industry
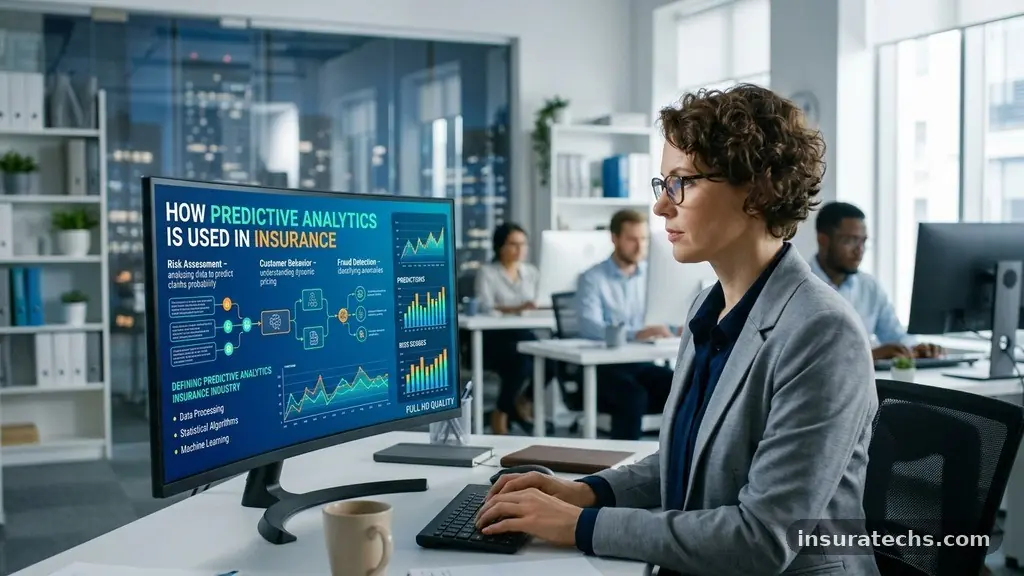
At its core, predictive analytics involves using historical data, statistical algorithms, and machine learning techniques to identify the likelihood of future outcomes. In the context of the insurance industry, it serves as the bridge between raw information and actionable business intelligence. Rather than guessing what might happen based on broad averages, firms now build granular profiles of risk.
These models process variables that go far beyond simple demographic data. They ingest information from telematics devices in cars, smart home sensors, and even public records to create a dynamic picture of risk. By running millions of simulations, insurers can predict the probability of a specific event—such as a property fire or a vehicle collision—with remarkable precision.
The shift toward data-driven decision-making has fundamentally changed the internal structure of major carriers. Departments that once operated in silos now share integrated datasets, ensuring that the information used by an actuary in pricing is consistent with what a claims adjuster sees in the field. This alignment reduces administrative overhead and improves the accuracy of financial forecasting across the entire organization.
Transforming Underwriting Through Data
Underwriting is the process of evaluating risk to determine whether to provide coverage and at what cost. Traditionally, this was a manual, time-intensive process that relied heavily on static tables and human judgment. Today, predictive analytics allows for automated underwriting, where complex risks are assessed in seconds rather than days.
Insurers utilize machine learning models to analyze thousands of data points during the application process. These models look for non-obvious correlations that a human underwriter might overlook. For instance, a model might identify that certain lifestyle habits or geographic markers are stronger indicators of long-term health than traditional medical history alone.
This speed is a significant advantage for both the customer and the company. Because the system can instantly verify data against external databases, many policies are now issued in real-time. This reduces the friction of the buying journey, helping applicants get the protection they need without waiting for manual reviews or supplemental medical exams.
Refining Pricing Models for Personalized Premiums
One of the most visible ways that predictive analytics is used in insurance is through the personalization of premium pricing. Instead of grouping individuals into broad categories based on age or location, carriers can now offer prices that reflect an individual’s specific risk profile. This is often referred to as behavior-based pricing.
In the auto insurance sector, this is best exemplified by usage-based programs. Drivers install a small device or use a smartphone app that tracks their braking, acceleration, and time of day spent on the road. The data is then fed into an algorithm that calculates a risk score, which directly influences the premium paid by the driver.
This approach rewards safe behavior with lower costs, creating a direct incentive for policyholders to minimize risk. It also allows insurers to better understand the true cost of covering a policyholder, leading to more sustainable financial models. The transition from collective risk pooling to individual risk assessment is a hallmark of modern insurance.
Revolutionizing Fraud Detection
Fraud is a massive drain on the insurance industry, costing billions of dollars annually and driving up costs for honest policyholders. Predictive analytics has become the primary weapon in the fight against these illicit activities. By monitoring claims in real-time, insurers can flag suspicious behavior before a payment is even issued.
These systems look for anomalies in the data that might indicate a coordinated effort to deceive. For example, a model might detect that a series of claims from different locations share the same repair shop, phone number, or IP address. This pattern recognition is nearly impossible for human auditors to perform manually across millions of records.
The ability to detect fraud early saves companies significant capital, which can then be reinvested into product innovation or premium reductions. Furthermore, it allows for a tiered approach to claims processing. Simple, low-risk claims are fast-tracked for payment, while high-risk claims are routed to specialized investigative teams for a deeper look.
| Application Area | Primary Benefit | Data Source Used |
|---|---|---|
| Underwriting | Faster processing speed | Applicant history, public records |
| Claims Processing | Fraud detection efficiency | Historical patterns, network analysis |
| Pricing | Personalized premium rates | Telematics, IoT sensors, behavior data |
| Customer Retention | Reduced policy churn | Interaction logs, life event triggers |
Enhancing Claims Management Efficiency
When a customer files a claim, the primary desire is for a fast and fair resolution. Predictive analytics enables this by automating the triage process. When a claim is submitted, an algorithm immediately analyzes the severity and complexity of the incident to determine the best path forward.
In many cases, the system can determine that a claim is routine and authorize payment immediately, bypassing the need for a physical inspection. This is common in minor property damage cases where photo evidence is uploaded to an app. The National Association of Insurance Commissioners provides extensive resources on how these technological shifts impact consumer protections and industry standards.
By automating routine tasks, adjusters are free to focus on complex, high-value claims that require human empathy and nuanced judgment. This creates a hybrid model where the efficiency of machines and the intuition of people work in tandem. The result is a faster cycle time and a higher level of customer satisfaction.
Managing Long-Term Risk in Life Insurance
The application of predictive models in the life insurance sector is particularly nuanced. Because these policies are designed for long-term protection, underwriters must assess mortality risk over decades. Analytics helps by integrating lifestyle data and health trends to create a more accurate projection of longevity.
This allows insurers to offer more competitive products to people who demonstrate healthy habits. It also enables the development of wellness-focused insurance products. Some policies now include features that track fitness activity, providing small rewards or premium discounts to those who meet specific health milestones.
These tools also help insurers manage their overall portfolio risk. By understanding the demographic and behavioral trends of their client base, they can adjust their investment strategies and capital reserves. This foresight ensures that the company remains solvent and capable of meeting its obligations, even in the face of long-term economic shifts.
Addressing Ethical and Regulatory Challenges
While the benefits of data-driven insurance are clear, the industry faces significant scrutiny regarding ethics and privacy. The use of algorithms can inadvertently lead to bias if the underlying data sets contain historical inequalities. Regulators are increasingly focused on ensuring that predictive models are transparent and fair.
Insurers must balance the desire for precision with the need for data security. As they collect more information from IoT devices and digital footprints, the risk of data breaches grows. Maintaining consumer trust is paramount, requiring strict adherence to privacy laws and open communication about how information is used.
Industry leaders are responding by implementing “explainable AI” frameworks. These systems ensure that when a model makes a decision—such as denying a claim or increasing a premium—there is a clear, human-understandable explanation for why that decision was reached. This transparency is essential for maintaining the integrity of the insurance system.
- Data Privacy: Ensuring that sensitive personal health or driving information is encrypted and protected.
- Algorithmic Bias: Auditing models to prevent discriminatory outcomes based on protected characteristics.
- Transparency: Providing policyholders with clear insights into how their behavior impacts their risk score.
- Human Oversight: Maintaining a “human-in-the-loop” approach for complex or sensitive claim decisions.
Frequently Asked Questions
How does an insurer decide which data is relevant for predictive models?
Insurers look for variables that have a statistically significant correlation with the risk being assessed. They use iterative testing to determine which data points provide the most predictive power without violating privacy or fairness regulations.
Can I opt out of data collection programs like telematics?
Yes, most usage-based insurance programs are voluntary. While opting in may provide opportunities for discounts based on safe driving, you generally have the right to choose a traditional policy that does not track your real-time behavior.
Do predictive analytics models make mistakes?
Models are only as good as the data they are trained on, and they can occasionally produce inaccurate results or false positives. This is why human oversight remains a critical component of the claims and underwriting process, particularly for complex or high-stakes decisions.
Will predictive analytics make insurance more expensive for everyone?
Not necessarily, as the goal is to align premiums more closely with actual risk. While some high-risk individuals may see premium increases, low-risk individuals often benefit from more accurate, lower-cost coverage that reflects their safer behaviors.
Conclusion
The integration of predictive analytics into the insurance industry represents a fundamental evolution in how risk is understood and managed. By leveraging vast amounts of data, insurers have gained the ability to provide more personalized, efficient, and proactive services. As these technologies continue to mature, the focus will increasingly shift toward balancing innovation with ethics and consumer privacy.
Understanding how predictive analytics is used in insurance empowers you to make informed decisions about your own coverage options. Whether it is through usage-based auto programs or wellness-oriented life insurance, the data-driven future of the industry offers significant potential for those willing to engage with it. Stay informed about your policy terms, and don’t hesitate to ask your provider how they use data to determine your risk profile and premium costs.