What Is Insurtech? A Simple Guide to Insurance Technology
Insurtech? A Simple Guide to Insurance Technology is the best way to understand how modern digital tools are reshaping the traditional world of risk management. By combining the words “insurance” and “technology,” this field focuses on using software to make buying coverage, filing claims, and managing policies much faster for everyday clients.
Whether you are a policyholder looking for a smoother experience or someone curious about industry trends, this overview explains how these digital innovations are changing the way insurance companies operate. You will learn how data-driven decisions and automated processes are replacing the slow, paper-heavy workflows of the past.
Defining the Core Concept
At its heart, insurtech refers to the use of technological innovations to squeeze out savings and efficiency from the current insurance industry model. Traditional firms often rely on legacy systems that have not seen significant upgrades in decades, leading to slow processing times and high operational costs.
Startups and established carriers alike are now adopting cloud computing, artificial intelligence, and machine learning to bridge these gaps. By leveraging these tools, providers can offer more personalized coverage options that fit the specific needs of individual customers.
The primary goal is to remove friction from the entire policy lifecycle, starting from the first quote to the final payout. When you request a quote through a modern digital platform, algorithms analyze your information in seconds rather than days. This speed is a direct result of insurance technology being integrated into the backend systems that calculate risk.
Instead of relying on manual data entry, these systems pull information from various digital sources to provide accurate pricing instantly. This shift makes the process less intimidating for consumers who might otherwise find insurance confusing or overly bureaucratic.
How Data Transforms Risk Assessment
Modern insurance companies are shifting away from broad, generic risk pools toward hyper-personalized models. In the past, actuaries looked at massive demographic groups to determine the likelihood of a loss, which often resulted in unfair pricing for lower-risk individuals.
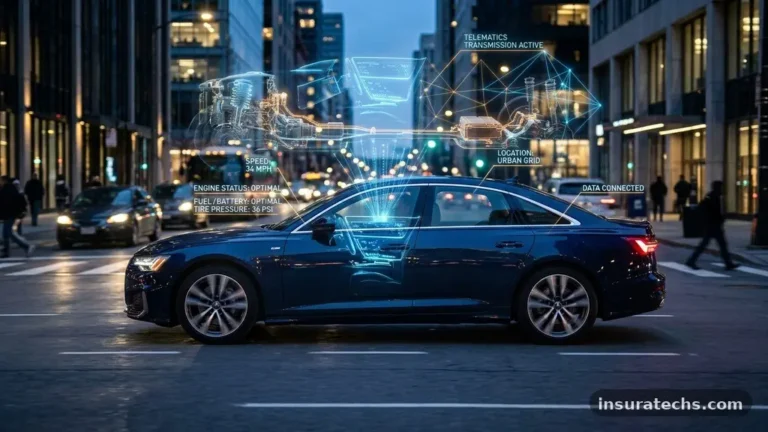
Today, data collected from connected devices allows for much more precise underwriting. For example, telematics devices installed in vehicles can track actual driving habits, such as hard braking or speeding, to adjust premiums based on real-world behavior.
This move toward behavior-based pricing is one of the most significant changes in the sector. It rewards careful customers with lower costs, creating a mutually beneficial relationship between the insurer and the policyholder. Beyond automotive coverage, this trend extends to home and health insurance as well.
Smart home sensors can alert homeowners to water leaks before they cause major damage, which minimizes the risk of a massive claim. When technology helps prevent a loss from happening, both the insurance company and the client win.
Streamlining Claims Processing
Filing a claim has historically been the most frustrating part of the insurance experience for many people. It typically involves filling out long forms, waiting for an adjuster to visit, and enduring weeks of back-and-forth communication.
Insurtech solutions are turning this process on its head by utilizing mobile apps and image recognition software. Now, a customer can often take a photo of damage—like a dented bumper or a broken window—and upload it directly to the company’s portal.
Artificial intelligence then reviews these images to estimate the cost of repairs almost immediately. This automation significantly reduces the time it takes to settle a claim, which is vital when a client is dealing with an stressful situation.
By reducing the reliance on manual labor, companies lower their administrative overhead and pass those savings on to the consumer. The following table highlights the difference between traditional workflows and modern digital-first methods.
| Process Phase | Traditional Method | Modern Digital Method |
|---|---|---|
| Policy Purchase | Manual agent consultation | Instant online quoting |
| Data Collection | Static forms and surveys | Real-time IoT/Telematics |
| Claims Filing | Paper forms and phone calls | Mobile app image upload |
| Payout Speed | Several weeks | Hours to few days |
The Rise of Digital-First Insurance Agencies
A new wave of companies has emerged that operate entirely online, bypassing the traditional brick-and-mortar agency model. These digital-first providers prioritize user experience, offering apps that allow customers to manage every aspect of their coverage from a smartphone.
They often provide 24/7 access to support through chatbots, which handle routine questions about billing or coverage details. By removing the need for physical offices and extensive administrative staff, these companies operate at a lower cost structure.
These digital agencies are particularly popular with younger generations who expect the same level of convenience they get from banking or shopping apps. They want to buy a policy in three clicks and check their status without waiting on hold for twenty minutes.
While these companies are tech-heavy, they are still subject to the same regulatory oversight as traditional insurers to ensure that client funds remain protected. You can find more information about these regulatory standards through the National Association of Insurance Commissioners, which monitors industry compliance.
Key Technologies Driving Innovation
Several specific technologies act as the engine for the current growth in the sector. Artificial intelligence and machine learning stand at the forefront, as they allow for the rapid analysis of vast datasets. These systems detect patterns that human underwriters might miss, which leads to better risk prediction.
Meanwhile, blockchain technology is beginning to play a role in security and transparency. By creating an immutable ledger for policy documents and claims, blockchain can reduce fraud and make the verification process much faster.
* Telematics: Sensors that track real-time behavior for better pricing.
* AI Chatbots: Automated tools that answer basic customer inquiries instantly.
* Computer Vision: Software that assesses damage from photos to speed up claims.
* Cloud Computing: Infrastructure that allows for massive data storage and scalability.
* Predictive Analytics: Models that anticipate future risks before they occur.
These technologies do not just help the companies; they provide tangible benefits to the users by creating a more transparent and responsive environment. When you interact with a modern policy portal, you are seeing these various technologies working in tandem to keep your data secure and your experience simple.
Challenges Faced by the Industry
Despite the rapid growth, the transition to a fully digital model presents several hurdles. Cybersecurity is the most pressing concern, as insurance companies hold vast amounts of sensitive financial and personal data.
As these firms become more reliant on digital infrastructure, they become higher-value targets for hackers. Protecting customer information requires constant investment in encryption and threat monitoring, which adds to the operational costs for any tech-driven company.
Another challenge involves the legacy systems mentioned earlier. Many established, large-scale insurers have decades of institutional data stored in outdated formats that are difficult to migrate to modern cloud platforms. This digital transformation is not as simple as flipping a switch; it requires careful planning and significant capital investment.
Finally, there is the issue of trust. While younger customers are comfortable with digital-only interactions, many people still value the face-to-face relationship with a local agent when navigating complex life insurance or liability policies.
Future Trends to Watch
The future of insurance will likely involve even deeper integration with the “Internet of Things” (IoT). As more household items become connected to the internet, insurers will have access to more granular data than ever before.
This could lead to a world where your refrigerator notifies your insurance provider if a pipe bursts, allowing for proactive repairs before a major flood occurs. Such preventative models shift the industry from being a reactive safety net to an active partner in risk mitigation.
Additionally, the rise of “embedded insurance” is changing how people buy coverage. Instead of going to a separate website, you might be offered tailored insurance the moment you purchase a plane ticket or a new laptop.
This seamless integration makes it easier for customers to get the protection they need without going out of their way. As these systems become more sophisticated, the line between technology and insurance will continue to blur, making the entire ecosystem more efficient for everyone involved.
Common Questions About Insurance Technology
It is the use of digital tools and software to make insurance faster, cheaper, and easier for customers to manage. Instead of paper forms and long waits, you use apps and automated systems to handle your policies.
Is insurtech legit?
Yes, it is perfectly legitimate. These companies are generally subject to the same strict financial regulations and state-level licensing requirements as traditional insurance providers.
Does using insurtech save money?
Often, yes. By reducing the administrative costs associated with manual paperwork and physical offices, these companies can often offer more competitive premiums to their clients.
How do I know if an insurtech company is safe?
Always look for the company’s license information on their website and check if they are backed by reputable reinsurance partners. You can also search for their status with your state’s department of insurance.
Will I still have access to a human if I need help?
Most modern digital insurance providers offer a mix of automated tools and human support. While you might use a chatbot for simple tasks, you can usually reach a human representative for complex claims or coverage questions.
Final Thoughts
Understanding the evolution of the industry is essential for anyone who wants to make informed decisions about their coverage. By embracing the advancements within Insurtech?
A Simple Guide to Insurance Technology, you can take advantage of faster service, more accurate pricing, and a more user-friendly experience. These tools are not just meant for the companies themselves; they are designed to give you more control over your financial protection.
As you look for your next policy, consider exploring providers that prioritize digital accessibility. You will likely find that the convenience of an app-based experience makes managing your risk much less of a chore. Stay curious about how new technologies continue to develop, as the industry is moving toward a more proactive, efficient, and transparent future for all users.